C&C Research · Coming Soon
Look past the ticker.
Understand the business.
Go inside our Adobe research sample. See the business evidence, the valuation assumptions and what would make us change our mind.
Inside the Adobe sample
The reasoning.
Not just the rating.
Three excerpts from the October 19, 2026 report. Open any screenshot to read it at full size.
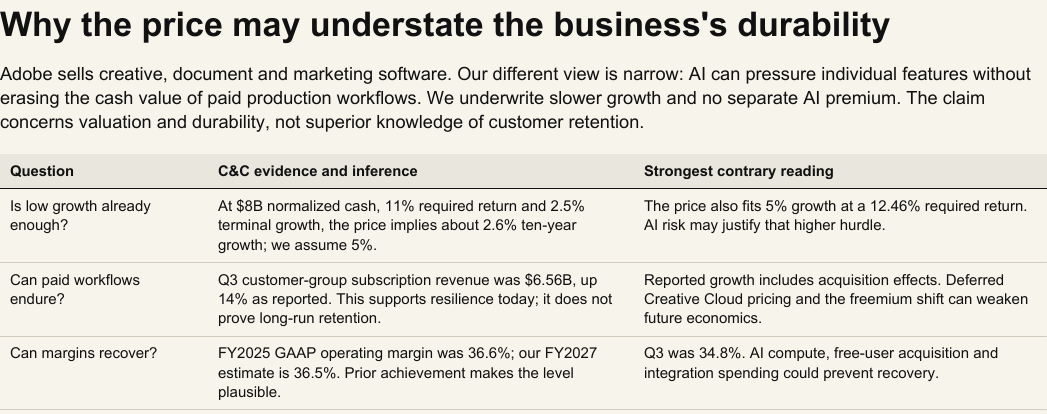
Our view, with the counterargument beside it.
Each question pairs C&C’s evidence and inference with a reason the market could be right. The distinction between reported facts and our judgment stays visible.
 Open screenshot ↗
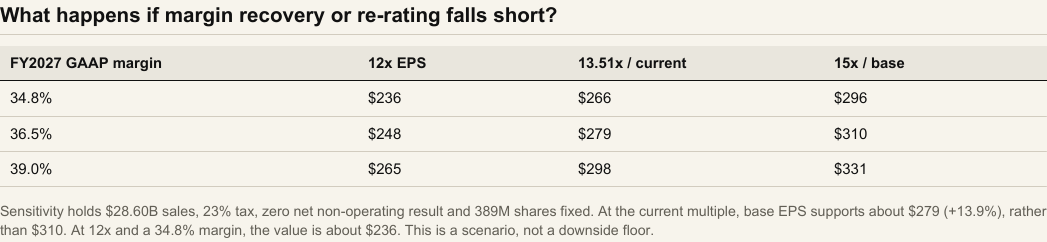
A target is only as useful as its assumptions.
See how changes in operating margin and the earnings multiple change the modeled outcome. The screenshot keeps the fixed inputs and downside qualification visible.
 Open screenshot ↗
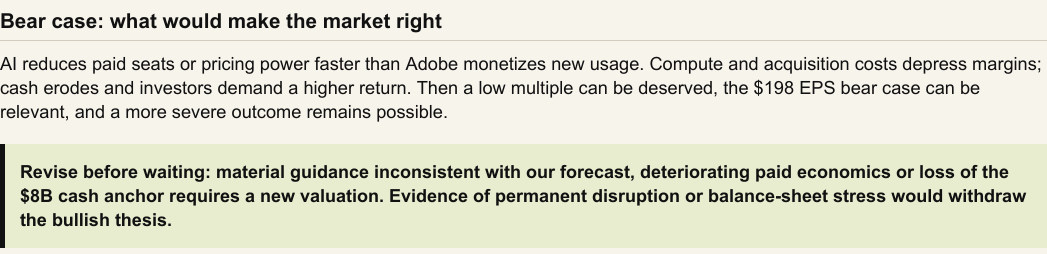
The case against us belongs in the report.
AI competition, pricing pressure and weaker cash generation can overturn the thesis. We set out what would require a new valuation or withdrawal of the bullish view.
 Open screenshot ↗
A dated research sample. These are selected excerpts, not the full report or a current quote. The report uses the October 16, 2026 completed-session reference close. Valuations and scenarios are C&C judgments, not company guidance, analyst consensus, promised returns or personalized investment advice.
Selected primary evidence: Adobe Q3 results and Q3 Form 10-Q. Our editorial standards.
Follow what comes next
Want more research
like this?
Join the C&C Research waitlist for launch updates and the Cash & Chaos newsletter. Already a reader? Use the same email to register your interest.
Joining is free. No payment is collected.